What Happens to Employees When a Veterinary Practice Is Sold?
or see an estimate: Veterinary valuation calculator →
For many veterinary practice owners, protecting the team matters as much as the purchase price. Employees may have helped build the hospital for years, supported clients through difficult moments, and kept the practice running through staffing shortages and emergencies.
So, what happens to employees when a veterinary practice is sold? In most viable transactions, the buyer wants the core team to stay. Veterinarians, technicians, client-service staff, assistants and managers carry clinical knowledge, client relationships, operating routines, and much of the practice’s day-to-day value.
But “the staff will stay” isn’t a complete answer. A sale can change who employs the team, how compensation and benefits work, who makes decisions, which systems are used, and what employees experience after closing. The outcome depends on the buyer, the transaction structure, the agreements negotiated before closing, and how the transition is communicated.
The best time to address these issues is before signing a letter of intent, not after the buyer has exclusivity and your alternatives have narrowed.
What happens to employees when a veterinary practice is sold?
Most buyers plan to keep the employees needed to run the practice after closing. A buyer is acquiring a functioning hospital, not an empty building. Losing the team would threaten appointment capacity, client continuity, medical quality, revenue, and the buyer’s investment.
That doesn’t mean every employee is guaranteed the same position or terms. The result usually falls into one of three categories:
- Continuation with limited change: employees stay in their roles while the buyer gradually introduces new systems, policies or benefits.
- Re-employment by the buyer: in an asset transaction, your employment relationships may end at closing and the buyer issues new offers, handbooks, benefit elections or agreements.
- Selective changes: the buyer keeps most clinical and support staff but changes certain management, administrative, duplicated or underperforming roles.
The legal mechanics vary by transaction structure and state law. In an equity transaction, the employing entity may stay in place even though ownership changes. In an asset transaction, the buyer may employ the team through a different entity. Coordinate employee issues with qualified legal and tax advisers rather than assuming the same process applies to every sale.
Why veterinary practice buyers usually want the team to stay
A stable team reduces transition risk. Buyers need people who understand the hospital’s clients, patients, schedule, equipment, vendors, medical protocols, pricing and culture. Replacing a whole team would be expensive and disruptive, especially where veterinarians and credentialed technicians are hard to recruit. The Association of American Veterinary Medical Colleges projects a shortfall of about 17,000 veterinarians by 2032, which makes an established team even more valuable to a buyer.
Associate veterinarian retention matters most, because doctor capacity supports revenue after the owner cuts back or leaves. Experienced technicians and assistants also create clinical leverage: strong support staffing lets each veterinarian see patients efficiently without sacrificing care.
The practice manager and long-tenured client-service team often hold knowledge that isn’t written down. They know how the schedule really works, which vendor relationships matter, how clients like to communicate, and where informal systems fill gaps in written procedures.
That’s why a strong buyer should discuss team continuity in detail. A vague promise that “nothing will change” is less useful than specific answers about roles, compensation, benefits, reporting lines, clinical decision-making and the transition plan.
What can change for employees after a veterinary practice sale?
Employment offers and job responsibilities
A buyer may ask employees to sign new offer letters, confidentiality agreements, restrictive covenants, arbitration provisions or handbook acknowledgments. Associate veterinarians may receive more detailed agreements covering compensation, production credit, schedules, time off, continuing education, liability insurance and post-employment restrictions.
Titles may stay the same while responsibilities shift. A practice manager who ran payroll, purchasing and HR may hand some of that to a central team while taking on more local operations. Employees should understand both the title and the actual role.
Compensation and production formulas
Hourly wages and salaries may stay the same at closing, but future raises, bonuses, overtime and production pay can change. For veterinarians, details such as negative accrual, production exclusions, discounts, refunds, lab charges and employee-pet benefits can materially affect take-home pay, even when the stated percentage looks familiar.
Ask the buyer to compare current and proposed compensation side by side, rather than relying on a general promise that pay will be “competitive.”
Health insurance, retirement and paid time off
A larger buyer may offer benefits an independent practice couldn’t: broader health plans, retirement matching, parental leave, continuing-education programs or formal career paths. Other changes may be less favorable: different premiums, deductibles, networks, waiting periods, vacation policies or rules for carrying over accrued time.
Compare benefits using actual plan details, not just a list of categories. Plan for enrollment, waiting periods and any gap between old and new coverage.
Scheduling, workload and clinical autonomy
Employees often care more about daily working conditions than about who legally owns the practice. A buyer may change appointment lengths, doctor schedules, weekend coverage, staffing ratios, pricing authority, inventory choices, purchasing rules or performance targets.
Veterinarians will want clarity on medical decision-making, referral discretion, formularies, production expectations and appointment times. Technicians and support staff may care about patient volume, how their skills are used, training, supervision, and whether positions will be added or removed.
Systems, branding and reporting
A sale may bring new practice-management software, payroll, inventory controls, pricing tools, financial reporting, cybersecurity requirements and policies. The hospital may keep its local name or eventually rebrand. Employees may report to the same local manager, a regional operator, or both.
These changes aren’t automatically good or bad. The question is whether the buyer has a credible integration plan, enough implementation support, and respect for what already works.
When should you tell employees about the sale?
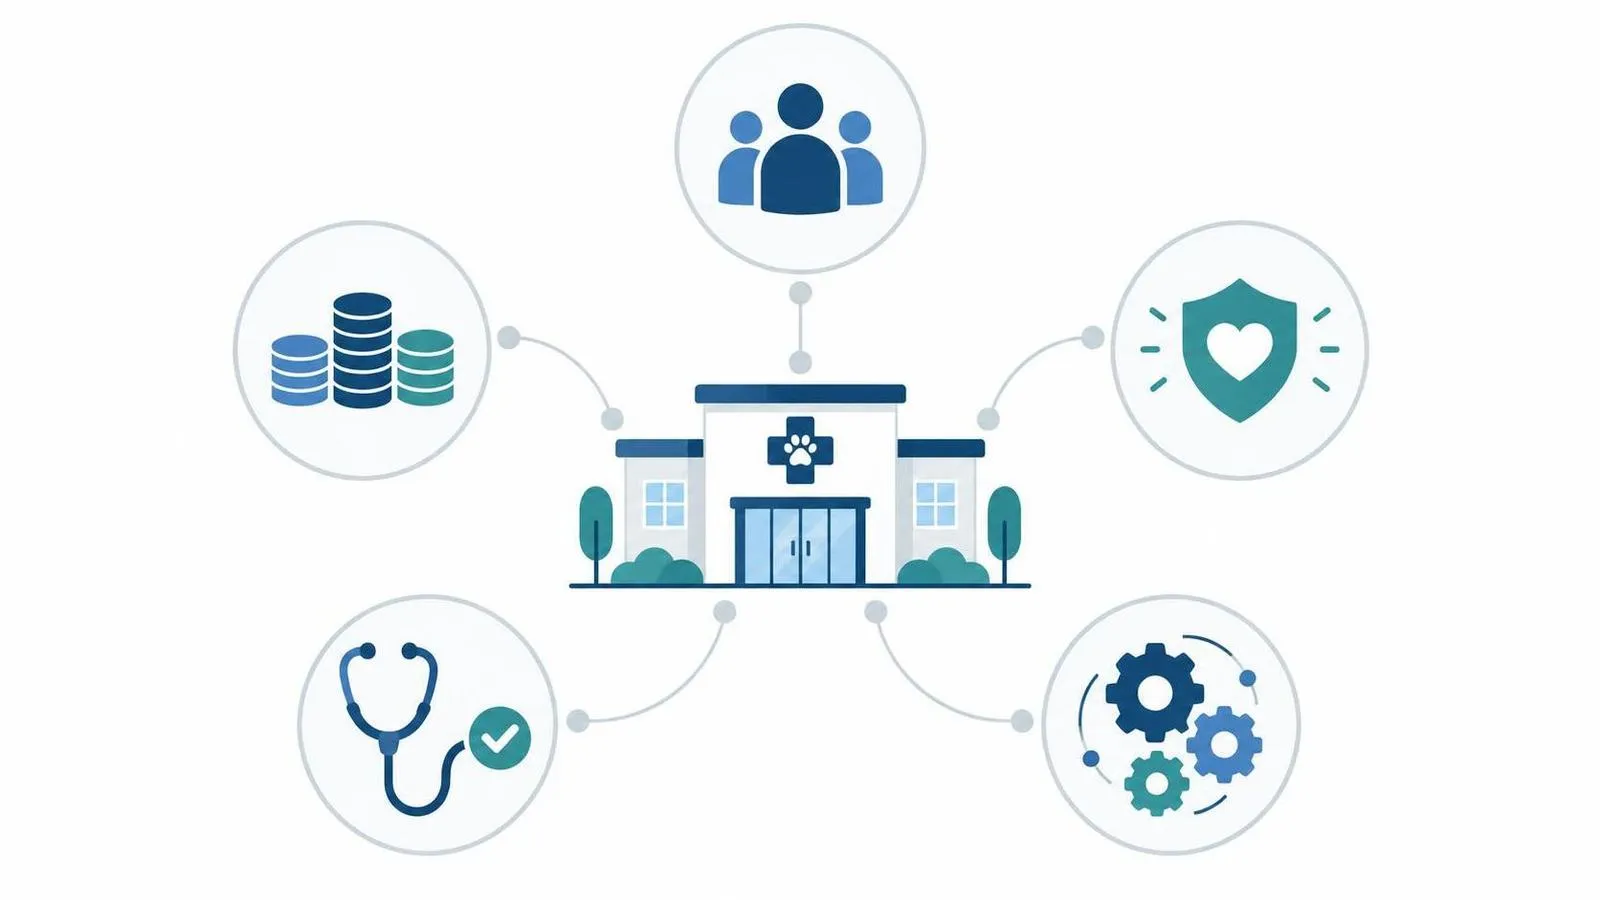
There’s no universal announcement date. Telling the whole team too early can create months of anxiety about a deal that may never close. Waiting until the last moment can leave loyal employees feeling blindsided, with too little time to evaluate new terms.
A practical plan often uses staged disclosure:
- Early exploration: keep the process to yourself and essential advisers. Share only anonymized information with qualified buyers.
- Serious negotiations: identify which key employees, if any, must be involved to confirm retention or answer diligence questions, with appropriate confidentiality.
- High confidence of closing: prepare the team announcement, individual employment materials, benefit information, and a way for employees to ask questions.
- Announcement and transition: explain what’s known, what’s changing, what’s staying the same, and where employees can get individual answers.
Timing may need to shift if a key associate veterinarian must sign a new agreement before the buyer will close, if employment law requires advance notice, or if the structure creates specific obligations. You, the buyer and your legal advisers should agree who communicates what, and when.
Confidentiality matters throughout. Our guide to selling a veterinary practice confidentially explains how staged disclosure protects the hospital while still giving buyers what they need.
Questions to ask buyers about your employees
Go beyond “Will you keep my staff?” and ask questions that reveal the buyer’s actual operating model:
- Which employees do you expect to keep, and are any roles likely to change?
- Will employees receive new offer letters or employment agreements?
- How will current wages, bonuses and veterinarian production formulas compare?
- What health, retirement, paid-time-off, continuing-education and employee-pet benefits will you offer?
- Will accrued vacation or sick time carry over?
- Who will control schedules, staffing levels, pricing, inventory and clinical protocols?
- Will the hospital keep its name, leadership and local identity?
- What systems will change, and how will employees be trained?
- Do you use retention bonuses for associate veterinarians, managers, technicians or other key staff?
- How and when did you communicate previous acquisitions to their teams?
- Can I speak privately with owners who sold to you about turnover and integration?
Weigh the answers alongside price and deal structure. Two buyers may offer similar economics while creating very different outcomes for the team. For a broader framework, see how to find buyers for a veterinary practice and selling to private equity vs. an individual buyer.
Can you protect employees in the sale agreement?
You can often negotiate provisions on employee offers, pay continuity, benefit transitions, retention bonuses, severance, accrued paid time off and the timing of the announcement. Whether a buyer accepts them depends on the deal, the buyer’s policies and your leverage.
The most important protections belong in writing. A buyer’s verbal promise about culture or job security may be sincere, but leadership, budgets and conditions change. The purchase agreement, employment documents, disclosure schedules, retention arrangements and closing plan are where specific commitments belong.
Be realistic about what you can control after closing. A promise to keep every employee indefinitely may be impossible for a buyer to give. A workable approach might require offers to named employees on defined initial terms, a stated benefit transition, funded retention payments, or severance if a key role is eliminated within an agreed period. Experienced transaction counsel should draft and review the actual protections.
How employee retention affects veterinary practice value
Team stability doesn’t guarantee a particular price, but it strongly affects buyer confidence. A hospital with several productive veterinarians, capable managers, well-used technicians, documented procedures and low turnover is easier to transfer than one whose revenue and relationships depend on the selling owner.
Buyers may look at:
- How much revenue the owner produces versus associate veterinarians
- Whether associates have signed, current employment agreements
- Employee tenure and recent turnover
- Open positions and reliance on relief veterinarians
- Technician utilization and staffing ratios
- Whether pay is competitive for the local market
- Whether the practice manager can run things without constant owner involvement
- How much operational knowledge exists only in the owner’s head
If the practice is highly owner-dependent, a buyer may ask for a longer transition, lower the price, make part of the price contingent, or require a recruitment plan. Our guide to selling a single-doctor veterinary practice explains how owner dependence changes the buyer pool, and the veterinary valuation calculator shows how doctor coverage affects an educational estimate.
A team-protection checklist before choosing a buyer
- Define your priorities. Decide which team outcomes are essential and where you’re flexible.
- Document current terms. Organize pay, benefits, paid-time-off balances, contracts, tenure, licenses and key responsibilities.
- Identify retention risk. Work out which veterinarians, managers, technicians or client-service staff are essential to continuity.
- Compare buyers’ operating models. Look at practices the buyer already owns, not just its marketing.
- Negotiate before exclusivity narrows your leverage. Raise employee priorities before or during the letter-of-intent stage.
- Put material commitments in writing. Coordinate the purchase agreement, employment offers, benefits, retention plans and announcement timing.
- Communicate honestly. Don’t promise that nothing will change. Explain what’s known and give people a clear way to get individual answers.
- Support the handoff. Help the buyer understand the people, routines and relationships that make the hospital work.
Our checklist for preparing to sell covers the documents buyers ask for at each stage.
The buyer you choose shapes your team’s experience
What happens to employees when a veterinary practice is sold isn’t decided by price alone. A national group, a regional group, a local veterinarian, an associate and a private-equity-backed platform may each approach staffing, integration, benefits, clinical autonomy and culture differently.
You can’t remove every future uncertainty. But you can qualify buyers carefully, ask specific questions, compare operating models, negotiate material protections, and choose a transaction that reflects both your financial goals and the legacy you want to leave.
Right Fit Capital introduces veterinary owners privately to carefully selected buyers, so you can compare how each would treat your practice and your team. See how matchmaking works, learn more about selling a veterinary practice, or get introduced to a buyer on a 15-minute call. There is no cost to the seller.