How Much Do You Make Selling a Veterinary Practice? Taxes, Deal Structure & Earn-Outs Explained
or see an estimate: Veterinary valuation calculator →
Every owner who has looked up what their practice might be worth asks the same follow-up question: but what do I actually walk away with? The answer is almost never the number on the offer letter. Between federal and state taxes, deal structure, earn-outs and closing costs, the gap between the sale price and your net proceeds can run to hundreds of thousands of dollars.
This guide explains how much you make selling a veterinary practice. Not the headline number, but the take-home, so you can plan your exit with clarity instead of surprises. It is general information, not tax or legal advice: your CPA and attorney should model your own numbers.
The gap between sale price and net proceeds
A practice that sells for $1.5 million doesn’t put $1.5 million in the owner’s pocket. Taxes, transaction costs, debt payoffs and deal structure all reduce it. In the illustrative example later in this guide, the owner keeps about 60% of the price. That share moves up or down mostly because of decisions made before and during the transaction.
Knowing where the money goes affects how you negotiate, which buyers you choose, and when you sell. If you don’t yet have a starting point for the price itself, the veterinary valuation calculator gives an educational estimate in about a minute.
How much do you make selling a veterinary practice? The tax picture
Taxes are usually the largest reduction between your sale price and your net proceeds. The amount depends on the deal structure, your entity type, and how the purchase price is allocated across asset categories.
Asset sale vs. stock sale
Most veterinary practice sales are structured as asset sales, not stock sales, and the distinction matters for your tax bill.
- Asset sale: the buyer purchases specific assets: equipment, client records, goodwill, the practice name. Each category is taxed differently. Most buyers prefer this because they get a stepped-up tax basis.
- Stock sale: the buyer purchases your ownership shares. You pay capital gains tax on the difference between your basis and the price. It’s simpler and often better for the seller, but many buyers resist it because they inherit the entity’s liabilities.
The structure is negotiated, not dictated. Knowing which one you’re dealing with matters, because it shapes everything that follows.
Purchase price allocation
In an asset sale, buyer and seller allocate the price across categories and report it on IRS Form 8594. Each category is taxed differently:
- Tangible assets (equipment, furniture, vehicles): taxed as ordinary income up to the depreciation you’ve already deducted (“depreciation recapture” under Section 1245). Federal ordinary rates reach 37%.
- Real estate (if included): unrecaptured depreciation is taxed at up to 25% (Section 1250), with any remaining gain at long-term capital gains rates.
- Goodwill: taxed at long-term capital gains rates (0%, 15% or 20% federal). This is usually the most favorable category for the seller.
- Non-compete agreement: taxed as ordinary income. Buyers like allocating to it because they can amortize it; sellers should resist an excessive allocation here.
- Accounts receivable: taxed as ordinary income if not previously reported.
Why it matters: the same price can produce very different tax bills depending on how much is allocated to goodwill versus equipment and the non-compete. Allocation is one of the most negotiable, and most overlooked, parts of a deal.
Depreciation recapture
If you’ve written off equipment, vehicles and leasehold improvements over the years, the IRS takes some of that benefit back when you sell. The part of the price attributed to previously depreciated assets is taxed at ordinary income rates, not capital gains rates. Owners who have equipped their practice heavily are often surprised by the size of this line.
State taxes
Federal tax is only part of the picture. State income tax on the gain ranges from nothing in states such as Texas, Florida and Nevada to top marginal rates above 10% in California, New Jersey and New York. On the same price, an owner in a high-tax state can pay well over $100,000 more than an owner in a state with no income tax. Some states also tax capital gains separately, so check your own state’s rules.
The 3.8% net investment income tax
If your modified adjusted gross income is above $200,000 (single) or $250,000 (married filing jointly), you may also owe the 3.8% net investment income tax on part of the gain. Whether it applies to a practice sale depends on how actively you work in the business and how the sale is structured, so ask your CPA. Most owners clear the income threshold in the year of a sale.
Deal structure: lump sum, installments or earn-outs
How and when you get paid matters as much as how much. Structure affects your tax, your risk and your cash flow after closing. Our guide to deal terms and retention periods goes deeper on each.
All cash at closing
The simplest and safest structure. You receive the price, less any escrow holdback, at closing. All taxable income lands in one year, which can push you into higher brackets, but you carry no risk that the buyer fails to pay later.
Suits: owners who want a clean break, and smaller deals where spreading the tax gives little benefit.
Seller financing (installment sale)
You’re paid over several years, plus interest. Under IRS Section 453, you can often spread the taxable gain over the payment period, which may keep more of it in lower brackets. Depreciation recapture is still taxed in the year of sale.
The risk: you become a lender. If the practice struggles under its new owner, your remaining payments are at risk. Seller notes should be secured by practice assets, with personal guarantees where possible.
Earn-outs
An earn-out ties part of the price to the practice’s performance after the sale, usually revenue, client retention or EBITDA targets over one to three years. They’re common in deals with private-equity-backed buyers, who use them to share integration risk.
What to know:
- Earn-outs are often treated as additional purchase price, but payments tied to your continued employment can be taxed as compensation, at ordinary income rates. The wording matters.
- You have limited control over whether targets are met: the buyer now runs the practice.
- Negotiate objective, measurable benchmarks (gross revenue, not subjective measures).
- Include a dispute-resolution process.
- Ask for quarterly reporting on earn-out metrics, not just an annual statement.
Transaction costs
Beyond tax and structure, hard costs come out of your proceeds:
- Legal fees for seller-side counsel: the purchase agreement, allocation and employment agreement.
- Accounting and tax advice: transaction tax planning and Form 8594.
- A formal valuation, if you commission one.
- Adviser fees, if you use a broker or other adviser.
- Debt payoff: equipment loans, lines of credit and SBA loans are typically paid off from the proceeds at closing.
- Escrow holdback: part of the price may be held for a period after closing to cover claims. You get it back if nothing goes wrong, but not on day one.
Ask each adviser for a written estimate early, so these numbers sit in your plan before you see an offer.
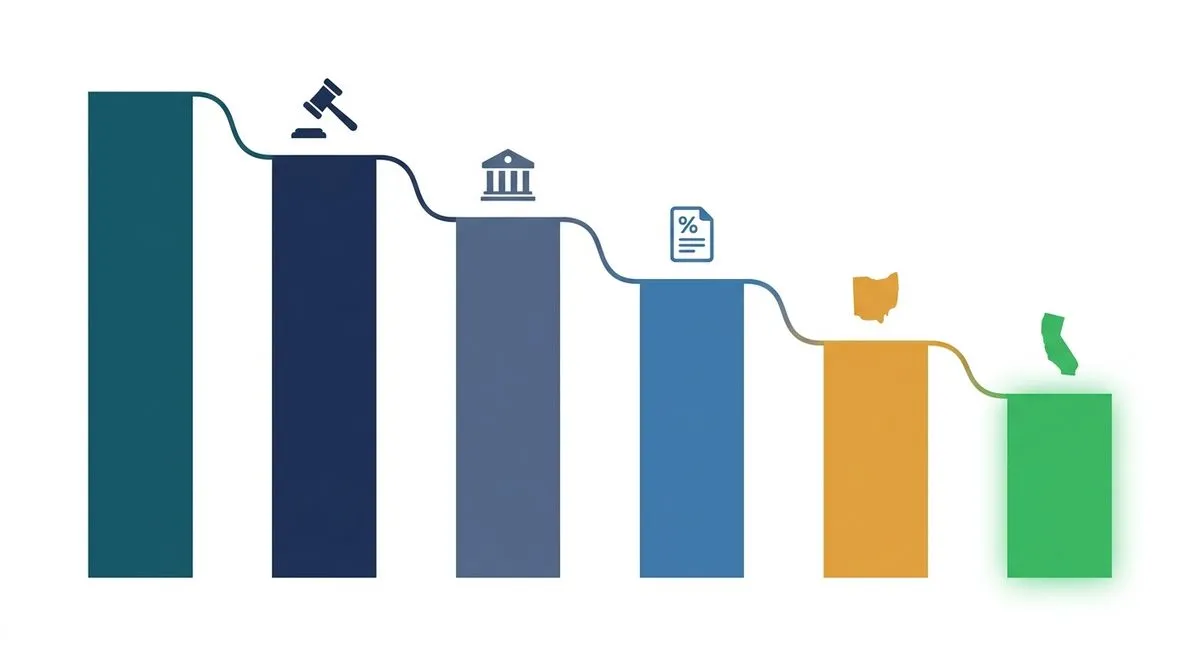
From sale price to take-home: an illustrative net proceeds waterfall.
An illustrative example: a $1.5 million practice sale
This is a simplified, hypothetical scenario to show how the pieces fit together. Real taxes depend on your basis, entity, income and state. Assume:
- A single-doctor practice owned through an S corporation, in a state with a 5.25% income tax
- An asset sale at $1.5 million
- Allocation: 55% goodwill ($825,000), 20% equipment ($300,000, with $200,000 of depreciation recapture), 15% non-compete ($225,000), 10% other ($150,000)
- All cash at closing
Estimated tax:
- Goodwill ($825,000): 20% federal capital gains plus 3.8% NIIT: about $196,000
- Equipment depreciation recapture ($200,000) at 37%: about $74,000
- Remaining equipment gain ($100,000) at 20%: about $20,000
- Non-compete ($225,000) at 37%: about $83,000
- Other ($150,000) at mixed rates: about $40,000
- State tax at 5.25%: about $68,000
Total estimated tax: about $481,000
Costs and payoffs:
- Legal: $25,000
- Accounting and tax: $10,000
- Valuation: $8,000
- Equipment loan payoff: $75,000
Total: about $118,000
Net proceeds: about $901,000, roughly 60% of the $1.5 million price. The same practice in a high-tax state, or with less goodwill in the allocation, would net noticeably less.
Five ways to keep more of the price
Knowing how much you make selling a veterinary practice is only useful if it changes your decisions:
1. Negotiate the purchase price allocation. Push for more of the price in goodwill (capital gains rates) and less in the non-compete and tangible assets (ordinary income rates). Give your attorney and CPA clear goals rather than leaving it to the closing documents.
2. Consider an installment sale. If the buyer is creditworthy and you don’t need all the cash at once, spreading the gain can lower your effective tax rate. Have your CPA run the numbers before you rule it out.
3. Structure earn-out terms carefully. Separate earn-out payments from any employment compensation, use objective benchmarks, and insist on regular reporting.
4. Compare complete offers, not headline prices. A higher price with a large earn-out, a heavy non-compete allocation or a long escrow can leave you with less than a lower all-cash offer. Model each offer’s after-tax result.
5. Reach more than one buyer. Competition between well-matched buyers improves price and terms. Our guide to finding buyers for a veterinary practice covers the options, and how matchmaking works explains how we introduce owners to qualified buyers. There is no cost to the seller.
When to start planning
The most common mistake is treating the financial side of a sale as an afterthought, something to sort out with your CPA after the offer arrives. By then, many of the most useful strategies are no longer available.
Ideally, start two to three years before you plan to sell:
- Review your entity structure (S corporation, C corporation or LLC) with your tax adviser.
- Understand how much depreciation recapture your equipment will trigger.
- Fund retirement accounts to reduce taxable income in the year of the sale.
- Clean up the financials and document owner-specific expenses, so buyers see the practice’s true earnings. Our veterinary practice valuation guide explains what buyers adjust for.
- If you own the building, decide early whether to sell or keep it: see veterinary practice real estate: sell it, lease it or hold.
Our checklist for preparing to sell lists the documents buyers ask for at each stage.
The bottom line
How much do you make selling a veterinary practice? It depends on how well you plan and negotiate the financial structure of the deal: your state, entity, allocation, payment terms and timing. The owners who walk away with the most aren’t always the ones with the highest prices. They’re the ones who understood where the money goes before the offer arrived.
If you’re considering a sale and want to talk through what buyers would look for in your practice, get introduced to a buyer on a 15-minute call. Right Fit Capital introduces veterinary owners to qualified buyers confidentially, and there is no cost to the seller. Learn more about selling a veterinary practice.