Veterinary Practice Earn-Outs and Retention Periods: What Happens After You Sell
For many veterinary practice owners, the hardest part of selling isn’t finding a buyer. It’s understanding what life looks like after the purchase agreement is signed.
That’s where the veterinary practice earn-out becomes one of the most important, and most misunderstood, parts of the deal. It can affect how much you ultimately receive, how long you keep working, how much control you keep, and whether the next chapter feels like a smooth transition or a slow-motion regret.
Most owners focus first on value and headline price. That makes sense, but it’s only part of the story. If a meaningful share of your payment depends on future performance, retention milestones, your continued employment or integration, the earn-out’s structure may matter almost as much as the price.
If you’re early in the process, start with the 7 early signs it might be time to sell and what your veterinary practice is worth. Once serious buyer conversations begin, ask a sharper question: what has to happen after closing for me to receive the full deal value?
What is a veterinary practice earn-out?
A veterinary practice earn-out is a structure where part of your payment depends on performance after closing, continued employment, retention or other agreed milestones. Instead of receiving the whole price at closing, you receive part upfront and the rest later if conditions are met.
Buyers use earn-outs to protect against risk: revenue falling after the owner leaves, key doctors departing, clients reacting badly to the ownership change, or margins shrinking during integration.
Earn-outs aren’t automatically bad. Well structured, they can bridge a valuation gap and let you share in the upside if the practice keeps performing. But a poorly written veterinary practice earn-out can shift too much risk onto you, especially once you no longer control the decisions that drive results.
Why buyers use earn-outs and retention periods
Veterinary practices are relationship businesses. A buyer isn’t just acquiring equipment, exam rooms, records and revenue history. It’s acquiring trust: from clients, staff, associates and the community.
That trust is often tied to the selling veterinarian. If you leave immediately after closing, buyers worry that clients will drift, staff will be unsettled, and associates will question the future. So buyers often ask you to stay involved for a transition period, commonly 2 to 5 years. Typical requirements include:
- Continuing as a practicing veterinarian
- Remaining clinical director during the transition
- Helping keep associate veterinarians and key staff
- Supporting client communication after the sale
- Maintaining certain production or revenue levels
- Taking part in integration with the buyer’s systems
From the buyer’s side, this is rational. From yours, it can be a major lifestyle issue. You may be selling for less stress, fewer management duties, more flexibility or a clear path to retirement, and a demanding retention period can undermine those reasons. Our guide to what happens to employees when a veterinary practice is sold covers the team side of the transition.
How a veterinary practice earn-out works
Structures vary by buyer, practice size, specialty mix, profitability and market conditions, but most fall into a few categories.
1. Revenue-based earn-out
You’re paid if the practice maintains or exceeds a revenue target after closing. Revenue is easier to measure than profit, but not risk-free: pricing changes, scheduling policies, marketing, doctor availability, client attrition and service mix all affect it.
Understand exactly how revenue is calculated, which period is measured, whether emergency or specialty revenue is included, and how unusual events are treated.
2. EBITDA or profit-based earn-out
Payment depends on EBITDA, operating income or another profit measure. This can align incentives, but it leaves more room for disagreement. After closing, the buyer may change staffing, pay structures, vendor contracts, management fees, software, rent allocations or overhead. Those decisions affect profit even when the practice is healthy.
If you won’t control expenses after closing, a profit-based earn-out needs especially careful drafting.
3. Retention-based earn-out
Payment depends on you staying for a defined period or helping keep key team members. It’s common where the owner is still a major producer, or where associate retention is a central concern.
It sounds simple, but the details matter. What counts as continued employment? What if health issues arise? What if the buyer materially changes your schedule, pay, duties or working conditions? What if an associate leaves for reasons outside your control?
4. Rollover equity with future upside
Some buyers, especially private-equity-backed platforms, ask you to roll part of your proceeds into equity in the acquiring company. It isn’t always called an earn-out, but it has a similar effect: part of your outcome depends on performance after closing.
Rollover equity can pay off if the buyer executes well and later sells at a higher value. It can also be illiquid, hard to value, and dependent on decisions far outside your control. Before assuming the highest headline offer is best, read selling to private equity vs. an individual buyer.
The biggest risk: losing control after closing
The central issue in any veterinary practice earn-out is control. If your future payment depends on outcomes you can no longer influence, you’re carrying risk without the authority to manage it.
Suppose your earn-out is based on EBITDA in the first 24 months after closing. The buyer then changes staffing ratios, raises corporate overhead allocations, renegotiates vendor contracts, changes doctor pay, or introduces software that slows the workflow. Even with strong client demand, reported profit could fall below the threshold.
Or suppose it depends on revenue retention. If the buyer reduces appointment availability, changes pricing abruptly or handles client communication poorly, revenue may dip for reasons unrelated to your effort.
So push for terms that are measurable, objective and tied to factors you can reasonably influence. The cleaner the formula, the less room for disputes later.
Questions to ask before accepting an earn-out
How much of the total is paid upfront?
The larger the deferred share, the more risk you carry after closing. A strong headline value is less attractive if too much of it is contingent.
Exactly which measure determines payment?
Revenue, gross profit, EBITDA, doctor production, staff retention and client retention are very different measures, each with its own incentives and risks.
Who controls the decisions that affect it?
If the buyer controls pricing, staffing, vendor costs, scheduling, marketing, pay and overhead allocation, be cautious about any formula tied heavily to profit.
What happens if the buyer changes the business?
The agreement should address major operational changes, acquisitions, closures, service changes, accounting policy changes and management fees. Without that, disputes become likely.
What are your work obligations after the sale?
Clarify your schedule, clinical and management duties, emergency coverage, administrative expectations, vacation, pay, reporting lines and decision authority. Don’t rely on informal assurances.
What if you’re terminated without cause?
If your payout depends on staying employed, the agreement should say what happens if the buyer ends your employment or materially changes your role.
Retention periods: the lifestyle term owners underestimate
The retention period is often treated as a footnote. It shouldn’t be.
For many owners, the employment agreement decides whether the sale feels successful day to day. A two-year retention period can be reasonable with clear duties, fair pay, autonomy and a realistic schedule. It can be miserable if it recreates the stress you wanted to leave, now with less control.
Clarify:
- Required weekly clinical hours
- Administrative and leadership duties
- Whether you remain clinical director
- Decision rights over medicine, staffing and client experience
- Vacation and leave
- Pay during the transition
- Non-compete and non-solicit restrictions
- Whether your role can change without your consent
Owners sometimes assume life gets easier the moment the deal closes. It can, but it isn’t automatic. The purchase agreement, employment agreement and earn-out terms all need to support it.
When an earn-out can be worth accepting
An earn-out isn’t always a red flag. It may make sense when:
- The upfront payment already meets your financial goals
- The measure is objective and easy to verify
- You keep meaningful influence over the result
- The buyer has a credible integration track record
- The employment terms match the life you want
- The upside is large enough to justify the risk
In a competitive process, some buyers use earn-outs to stretch their offer. That can work if the practice is growing quickly and you’re happy to stay involved. But the upside should be real. If the path to the earn-out is vague, discretionary or dependent on buyer decisions, discount it.
When to push back
Push back when an earn-out shifts too much risk to you without enough control, transparency or reward. Warning signs include:
- A high headline price with a large contingent portion
- Profit targets without clear expense controls
- Broad buyer discretion over accounting policies
- Vague employment obligations
- Earn-out payments you lose if the buyer changes your role
- No clear reporting during the measurement period
- No protection if the buyer materially changes operations
These aren’t just legal details. They decide whether the deal you think you’re signing is the deal you actually get.
Negotiating better veterinary practice earn-out terms
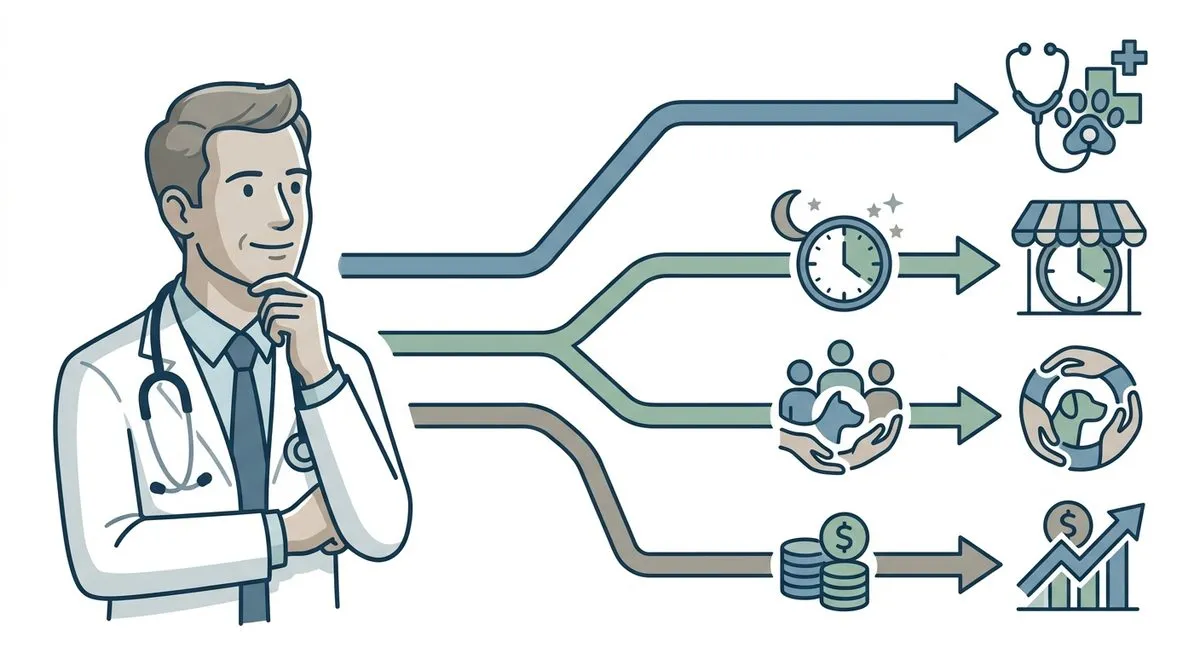
The best time to negotiate earn-out and retention terms is before exclusivity, while you still have more than one buyer. Once you sign a letter of intent and go deep into diligence with one buyer, your leverage narrows.
Useful negotiating points:
- More cash upfront
- A shorter earn-out period
- Revenue instead of profit, if the buyer controls expenses
- Neutral accounting rules for the measurement period
- Excluding buyer-imposed overhead from the calculation
- Protection if the buyer materially changes operations
- A detailed definition of your role
- Partial payout tiers instead of all-or-nothing thresholds
- Regular reporting during the earn-out period
The goal isn’t to reject every earn-out. It’s to understand what’s being asked of you and negotiate a structure that reflects reality. A buyer who wants a successful transition should be willing to make success measurable and fair.
Don’t compare offers on headline price alone
Two offers can look similar and be very different in practice. Offer A shows a higher total but includes a large earn-out, strict employment terms, aggressive profit targets and little control. Offer B shows a lower total but more cash at closing, cleaner transition terms and a role that fits your goals.
For many owners, the better offer isn’t the biggest number. It’s the best combination of price, certainty, culture, autonomy after the sale, and the likelihood of actually receiving the full value. Our guide to what you take home after selling a veterinary practice shows how structure and tax change the result, and the veterinary valuation calculator gives an educational estimate of the price itself.
The bottom line
A veterinary practice earn-out can be useful, but never accept one casually. It affects your financial outcome, your workload after the sale, your control and your peace of mind. Before signing, understand exactly how it’s calculated, what you must do to receive it, what the buyer can change after closing, and whether the retention period fits the life you want.
The surest way to get better terms is to have more than one serious buyer. Right Fit Capital introduces veterinary owners to qualified buyers so you can compare real offers before committing. There is no cost to the seller. See how matchmaking works, our checklist for preparing to sell, or book a 15-minute intro call.