Veterinary Practice Real Estate: Sell It, Lease It, or Hold?
or see an estimate: Veterinary valuation calculator →
Owning the hospital building creates a second exit decision that many veterinary practice owners don’t fully examine until a buyer is already at the table. You are not selling one asset. You are deciding what to do with two assets that are financially linked but valued in different ways: the operating practice and the veterinary practice real estate beneath it.
You can sell both to the same buyer, sell the practice and become the buyer’s landlord, sell the building to a separate real estate investor, or hold the property and sell it later. Each route changes your cash at closing, future income, tax exposure, buyer pool, financing options and responsibilities after the sale.
The short answer: selling the building with the practice usually creates the cleanest exit. Keeping the building can produce attractive rental income, but only if the lease is priced correctly, the property stays useful to the tenant, and you genuinely want the risks of being a commercial landlord. The highest combined headline price is not automatically the best economic result.
Model the decision before the practice goes to market. If rent, lease terms and building value are addressed late, the real estate can reduce the value of the practice, or become the issue that stops an otherwise qualified buyer from closing.
Why veterinary practice real estate is a separate deal
Buyers evaluate the practice on its transferable earnings, growth, doctor capacity, service mix, team stability and operating risk. They evaluate the property on real estate factors: location, condition, permitted use, market rent, comparable sales, replacement cost, and the income a tenant can support.
The distinction matters because the same rent connects both valuations. Rent is an expense to the practice and income to the property owner. Raising rent may make the building more valuable as an income-producing asset, but it lowers the practice’s earnings. Lowering rent may make practice EBITDA look stronger, but a buyer will usually normalize the expense to a defensible market rate.
Owners who hold the practice and the property in separate entities sometimes overlook this, because rent has always been an internal transfer. A buyer and its lender won’t. They will ask whether the practice can comfortably pay the proposed rent after payroll, inventory, equipment, debt service and normal reinvestment.
That’s why a practice valuation and a real estate appraisal should be coordinated. Treating either number on its own can produce an attractive result that doesn’t survive buyer or lender review. For the operating-business side, see our guide to what a veterinary practice is worth, or get an educational estimate from the veterinary valuation calculator.
Four ways to handle veterinary practice real estate in a sale
1. Sell the practice and the building to the same buyer
This route gives you a clean break and turns both assets into cash at closing. The buyer controls a specialized facility, avoids future lease-renewal risk, and benefits from any long-term appreciation. The transaction can also feel simpler, because one buyer coordinates the business and property diligence.
The main constraint is capital. An individual veterinarian may be able to finance the practice but not the real estate at the same time. A group or corporate buyer may prefer to lease so it doesn’t tie acquisition capital to property. Requiring a combined purchase can shrink the buyer pool, even when the building is desirable.
2. Sell the practice and lease the building to the buyer
You receive the proceeds from the practice and keep a potentially valuable income-producing property. The buyer uses less cash at closing and keeps the hospital where clients already know it. This can work well when you want dependable income and the facility has a long useful life.
But it isn’t a clean exit. You become a commercial landlord whose tenant’s ability to pay rent depends on the practice you just sold. Major repairs, lease negotiations, insurance, taxes, casualty risk and eventual vacancy remain real responsibilities. If the buyer later relocates, you may be left with a specialized animal-hospital building that is expensive to repurpose.
3. Sell the practice and the building to different buyers
A real estate investor may buy the property while the practice buyer signs a long-term lease. This can turn the building into cash without forcing the practice buyer to fund both acquisitions, and it can create price competition for the property.
The two transactions must be coordinated carefully. The practice buyer, the property buyer and their lenders all need compatible lease terms, diligence periods, closing conditions and assignment rights. A high property offer funded by aggressive rent can reduce practice value or make the practice harder to finance. The buyers are separate, but the economics are still joined.
4. Keep the building now and sell it later
Holding the property spreads your liquidity across two events and preserves future appreciation. It also gives you time to decide whether landlord income fits your retirement plan.
The trade-off is concentration and uncertainty. Much of the property’s value may depend on one veterinary tenant. The lease could expire during a weak real estate market, the tenant could ask for concessions, or the facility could need costly improvements. A later sale may produce more value, but it isn’t guaranteed.
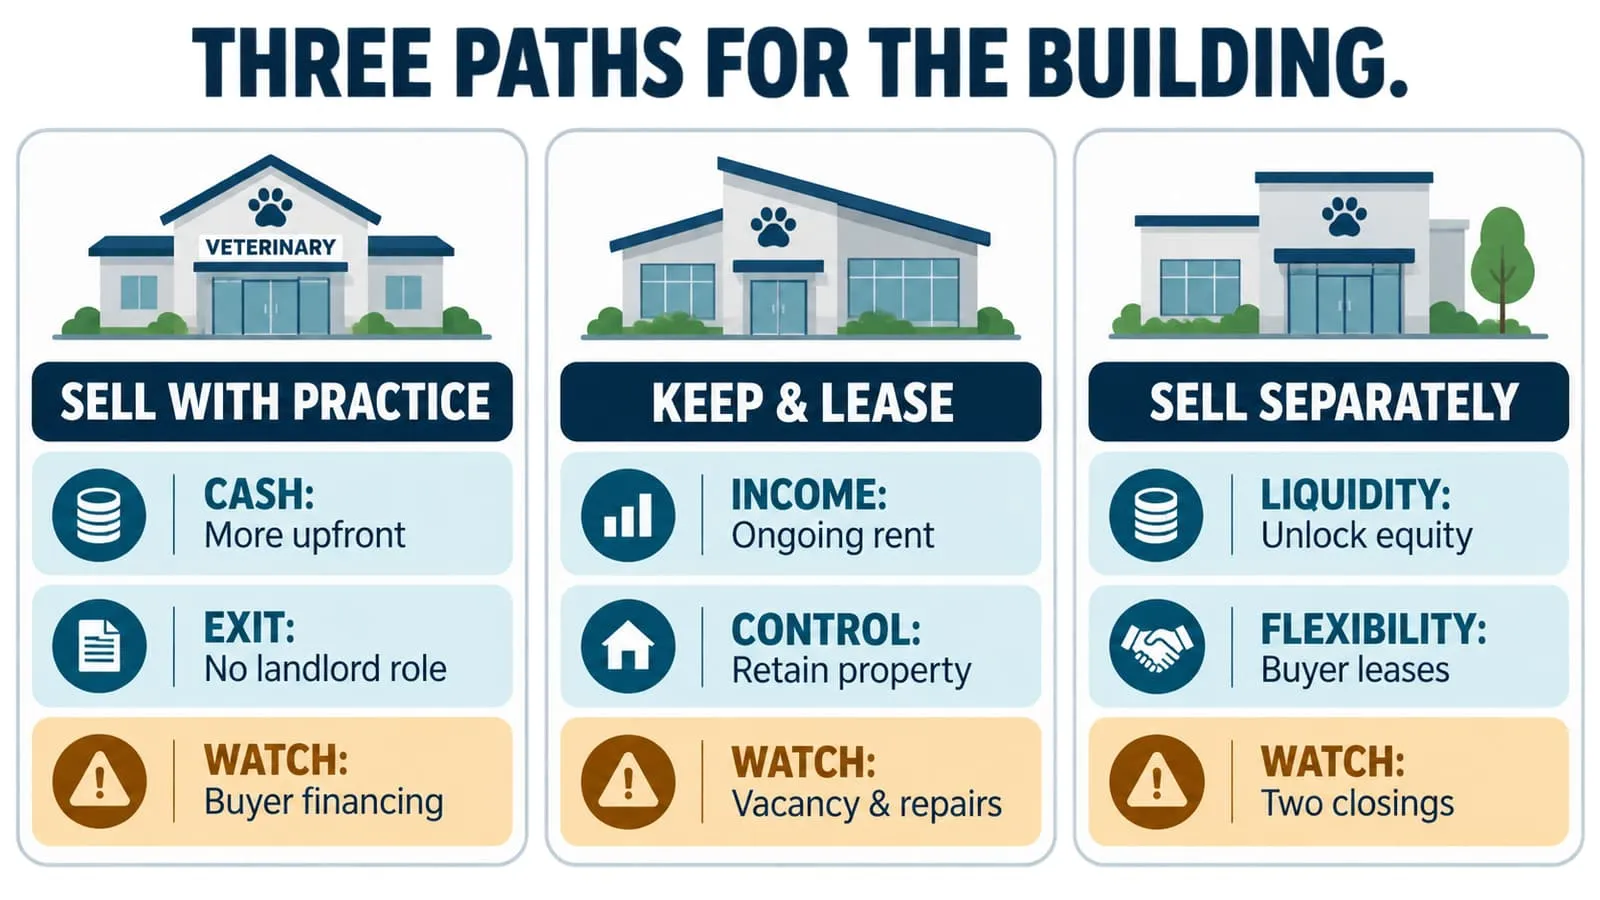
Selling, keeping and separately selling the building create different liquidity, income and risk profiles.
Market rent can move the practice price
Rent normalization is where owners most often double-count value. Imagine a practice reports $600,000 of EBITDA while paying $100,000 less than market rent to a property entity the seller owns. A buyer may reduce normalized EBITDA to $500,000. In this illustrative example, at eight times EBITDA, that $100,000 adjustment changes the indicated practice value by $800,000. Real multiples vary by buyer and practice; this is not a valuation.
The building may become more valuable under a market-rate lease, but that doesn’t automatically replace the full decrease in practice value. The result depends on the property’s capitalization rate, lease quality, expenses, location and tenant credit. You can’t fairly value the practice using below-market rent while valuing the building using higher market rent.
The reverse also happens. If the practice pays above-market rent to your property entity, normalized EBITDA may rise when the expense is adjusted down. But don’t assume a buyer will accept a new lease at the historical rate just because the practice paid it before.
The right exercise is to model both assets together:
- Set a defensible market rent with a qualified local commercial real estate professional.
- Recalculate practice EBITDA using that rent and ordinary occupancy expenses.
- Value the practice on its normalized operating performance.
- Value the property on its condition, location, permitted use, market evidence, lease economics and tenant quality.
- Compare after-tax proceeds and risk under each structure, rather than adding two optimistic headline values.
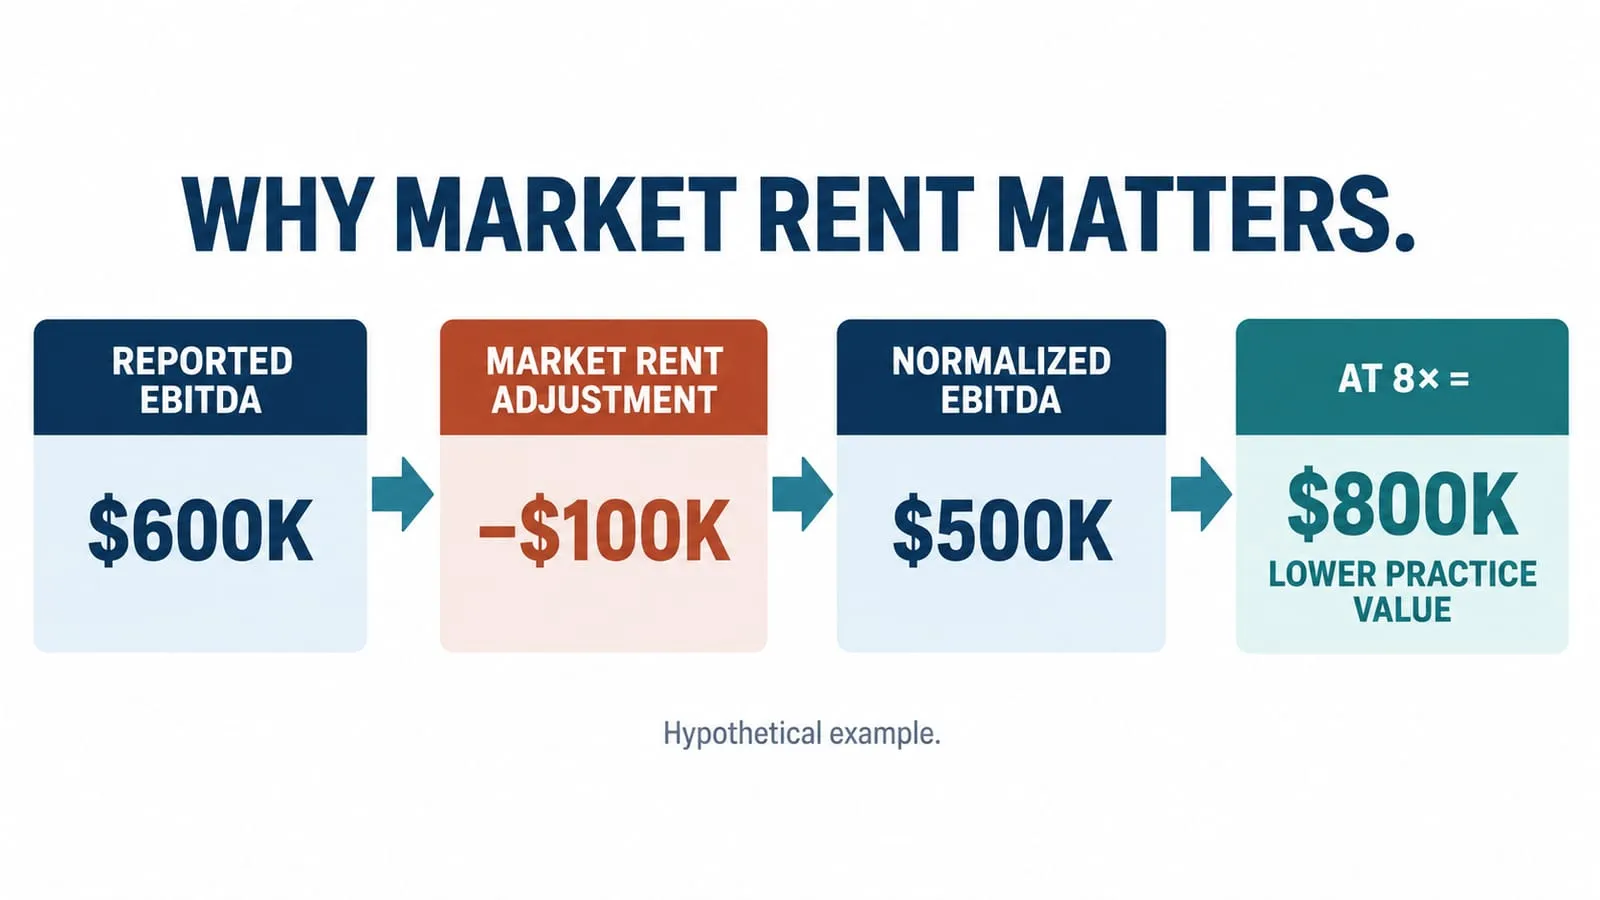
An illustrative example: a below-market rent adjustment can materially reduce normalized EBITDA and the indicated value of the practice.
Lease terms buyers and lenders will examine
When you keep the property, the lease becomes part of the acquisition, not an administrative detail to finish later. A strong lease protects you as the property owner without making the practice brittle or hard to finance.
Expect scrutiny of:
- Initial term and renewal options: the buyer needs enough site control to justify the acquisition and satisfy its lender. You need clarity about how long the property is committed.
- Base rent and increases: starting rent should be supported by market evidence and practice cash flow. Escalations shouldn’t outrun the hospital’s realistic growth.
- Repairs and capital expenses: the lease should clearly allocate the roof, structure, HVAC, plumbing, parking, specialized improvements and ordinary maintenance.
- Assignment and change of control: the buyer may need the right to assign the lease to an affiliate, lender or future acquirer. You will want reasonable financial protections.
- Use, exclusivity and compliance: veterinary operations may involve kennels, medical gases, radiology, pharmacy inventory, waste handling, exterior runs, noise, odor and around-the-clock access. The permitted-use language must match the actual hospital.
- Casualty, condemnation and insurance: both parties need a workable plan if the property is damaged or access is impaired.
- Personal or corporate guarantees: a guarantee’s value depends on who gives it, for how long, and what happens after a future ownership change.
- Purchase options and rights of first refusal: these can create a future path to ownership, but may complicate a later property sale.
A lease that maximizes rent on day one can weaken the practice’s borrowing capacity and long-term health. A lease that is too buyer-friendly can leave you with an underperforming asset and expensive obligations. Your real estate and transaction counsel should negotiate the balance.
Veterinary facilities carry unusual re-leasing risk
A veterinary hospital isn’t interchangeable with a typical office. It may include surgery suites, treatment areas, kennels, isolation rooms, floor drains, heavy electrical service, specialized HVAC, oxygen lines, radiology shielding, sound control, pharmacy storage and exterior animal areas. Those improvements can be valuable to another veterinary operator, but costly or irrelevant to anyone else.
Before choosing rental income over a clean sale, ask what happens if the buyer leaves after the first term:
- Could another veterinary tenant legally and economically operate there?
- Would zoning, parking, noise rules or permits limit another medical or animal use?
- How much would conversion to retail, office or another healthcare use cost?
- Could the tenant relocate nearby and make the original site less attractive to another veterinarian?
- Does the local market have enough alternative tenants to support the assumed property value?
The building may be an excellent investment, but the right comparison isn’t “rent versus no rent.” It’s risk-adjusted rental income and future value versus the net proceeds available from selling today.
How buyer type changes the real estate decision
An individual veterinarian may value ownership but need separate financing, more seller flexibility, or a delayed purchase option. A regional group may prefer a long lease to preserve acquisition capital. A private-equity-backed platform may avoid owning real estate but accept a lease that meets its investment and lender standards. A real estate investor may pay well for a long-term lease backed by a strong practice tenant.
No buyer type produces one universal answer. Financial capacity, site strategy, credit, expansion plans and expected ownership horizon matter more than the label. Compare complete proposals, not only the practice offer, and understand how each buyer intends to use the facility. Our comparison of private equity and individual practice buyers explains how buyer models can affect your outcome, and how matchmaking works shows how we find buyers whose real estate preferences fit yours.
Tax and estate planning should begin before the LOI
Selling a practice and selling real estate can create different federal, state and local tax consequences. Depreciation history, entity structure, purchase-price allocation, debt payoff, installment treatment, passive income and your estate plan can all affect net proceeds. A lease creates another income stream with its own expenses and tax treatment.
Have qualified tax and legal advisers model these questions before you accept a letter of intent. The offer with the largest total price can leave less spendable wealth after taxes, debt, deferred payments and ongoing property risk. Our guide to what you take home after selling a veterinary practice explains why the purchase price alone is an incomplete measure.
A decision framework for veterinary practice owners
Selling both assets may fit best when:
- You want a clean exit with no landlord responsibilities.
- The buyer can finance both assets without weakening the practice deal.
- The property is too large a share of your retirement portfolio.
- The facility may need significant capital work.
- You prefer certainty over potential appreciation and rental income.
Keeping and leasing the property may fit best when:
- You want long-term income and are comfortable remaining a landlord.
- The tenant is financially strong and the lease is durable.
- Market rent works for both the property’s value and the practice’s cash flow.
- The building has a long useful life with manageable capital needs.
- The site has credible alternative uses or tenants if the practice eventually moves.
A separate property buyer may fit best when:
- You want to turn the building into cash without requiring the practice buyer to buy it.
- The practice buyer will sign a financeable long-term lease.
- A coordinated process can protect the practice sale from rent or timing conflicts.
- The combined after-tax outcome beats the alternatives without adding unacceptable closing risk.
Plan the practice and property exit as one strategy
Veterinary practice real estate can create flexibility, income and additional wealth. It can also narrow the buyer pool, distort EBITDA, complicate financing, and leave a retired owner exposed to a highly specialized building. The difference comes down to planning the practice, property, rent, lease, taxes and buyer strategy together.
Before going to market, get a defensible view of market rent, normalize the practice’s financials, assess the building’s future capital needs, and compare the after-tax economics of selling versus holding. Then look for buyers whose real estate preferences fit your goals. Our checklist for preparing to sell covers the documents buyers ask for.
Right Fit Capital introduces veterinary owners to qualified buyers confidentially, and helps you compare the full structure of an offer, not only the number at the top. Learn more about selling a veterinary practice, or get introduced to a buyer on a 15-minute call.